
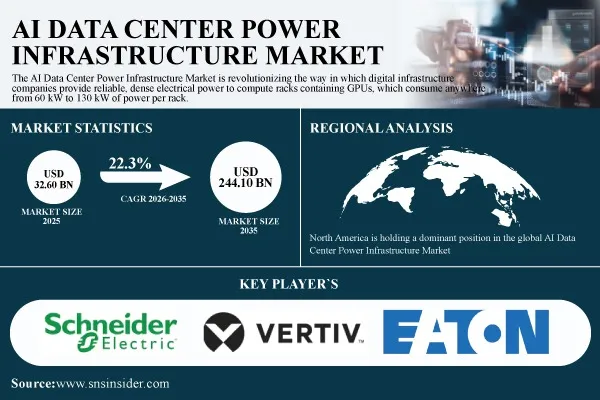
U.S. AI Data Center Power Infrastructure Market to Reach USD 97.00 Billion by 2035 as North America Leads and Asia Pacific Records the Fastest Growth at 26.90% CAGR
Austin, Sept. 14, 2026 (GLOBE NEWSWIRE) -- According to SNS Insider, the AI Data Center Power Infrastructure Market was valued at USD 32.60 Billion in 2025 and is projected to reach USD 244.10 Billion by 2035, registering a CAGR of 22.3% from 2026 to 2035. Market expansion is attributed to increased hyperscale AI campuses, growing power density of GPU racks from approximately 60 kW to 130 kW, increased use of 800 volts DC power systems and increasing use of onsite power generation solutions. Investments by utilities in the construction of dedicated transmission lines and increased procurements of high-capacity UPS, switchgear, transformers and distribution systems are also boosting the expansion of AI data center infrastructure.
In 2026, Bloom Energy made a master services agreement with Oracle worth 2.8 gigawatts of solid oxide fuel cells for powering AI data center campuses, a move that significantly increased its previous 1.2-gigawatts deal. Eaton also revealed almost 20 pilot projects for its medium-voltage solid-state transformer technology that supports 800-volt DC power distribution system, with orders for the same from hyperscalers in the second half of 2026 and shipment slated for late 2027.
Download the AI Data Center Power Infrastructure Market Sample Report: https://www.snsinsider.com/sample-request/10850
AI Data Center Power Infrastructure Market Key Highlights
- Market size, 2025: USD 32.60 Billion
- Market forecast, 2035: USD 244.10 Billion
- CAGR: 22.3% from 2026 to 2035
- Largest region: North America
- Fastest-growing region: Asia Pacific, at 26.90% CAGR from 2026 to 2035
- Largest component: UPS Systems, with 29% share in 2025
- Fastest-growing component: Power Distribution Units
- Largest power capacity: Above 20 MW, with 41% share in 2025
- Fastest-growing power capacity: 10–20 MW
- Largest data center type: Hyperscale, with 55% share in 2025
- Fastest-growing data center type: Colocation
- Largest end user: Cloud Service Providers & Hyperscalers, with 59% share in 2025
- Fastest-growing end user: Government & Defense
Market Relevance
The power system infrastructure for AI data centers is emerging as an important consideration within the digital economy due to the increased electrical loads placed on data center facilities by accelerated computing environments. GPU-intensive racks need power systems that are dependable, scalable, and have large capacities so that they can support very high load densities without impacting availability.
AI Data Center Power Infrastructure Market Overview
The AI Data Center Power Infrastructure Market encompasses UPS, switchgear, power distribution units, transformers, substations, generators, fuel cells, busways, rack level distribution, and other power infrastructure necessary for AI-oriented data centers. The UPS segment continues to be the biggest part of the market as UPS has been traditionally used to offer N+1 or 2N redundancy for GPU workloads.
Strategic Market Outlook
On-site generation is a significant opportunity as the hyper-scale providers look for ways around long wait times in the queue of grid interconnection. Solid oxide fuel cells, gas turbines, and other distributed energy systems can serve as additional generation options for AI data centers while minimizing reliance on the limited regional grid infrastructure. Companies that have dependable and commercially validated on-site generation solutions will be well-placed to capitalize on the trend.
AI Data Center Power Infrastructure Market Regional Analysis
North America emerged as the major market for the AI Data Center Power Infrastructure Market during the period of 2025, owing to its major investments in AI hyperscale campus, power infrastructure players, utility capacity investments for transmission and substations, and grid modernization initiatives supported by the government. The value of the U.S. AI Data Center Power Infrastructure Market in 2025 was estimated at USD 13.49 billion and is expected to reach USD 97.00 billion in 2035 with a CAGR of approximately 21.8% between 2026 and 2035.
Asia Pacific is expected to register the highest CAGR of 26.90% in the forecast period of 2026-2035, which will be supported by increasing government investment in AI infrastructure, expansion of power equipment manufacturing capability, rising number of hyperscale campuses, and increasing AI computing demand in China, India, South Korea, and Southeast Asia. China accounted for around 33.50% share of Asia Pacific market in 2025.
Buy the AI Data Center Power Infrastructure Market Report with Competitive Analysis and 2035 Forecast: https://www.snsinsider.com/checkout/10850
AI Data Center Power Infrastructure Market Segment Analysis
By Component: The UPS System segment occupied the largest market share of 29% in 2025 due to its significance in safeguarding the GPU training clusters from any disruptions in power supply and providing support to N+1 and 2N redundancy architectures. The Power Distribution Units segment has been witnessing rapid growth owing to growing rack densities.
By Power Capacity: The above 20 MW segment had 41% of the total market share in 2025 due to investment from hyperscalers into AI campuses of huge scale that needed substations, power generation equipment, and heavy-duty switchgear. The 10-20 MW capacity range is experiencing the most rapid growth due to the deployment of AI-ready halls by colocation providers through modularity of power equipment.
By Data Center Type: Hyperscale data centers accounted for a dominant 55% in 2025 due to continuous capital expenditure by cloud computing service providers in the construction of AI training and inferencing infrastructures. Colocation is the quickest growing data center form as enterprises and midsize organizations are increasingly opting for colocation instead of building dedicated AI campuses.
By End User: The Cloud Service Providers & Hyperscalers segment captured a commanding 59% share of the market in 2025 because of their ownership of a significant amount of worldwide AI compute capacity and the fact that they can enter into long-term deals for power and equipment supply. Government & Defense is the most rapidly growing end-user vertical because of increased spending by sovereign AI initiatives in the U.S., EU, and GCC nations on local computing infrastructure.
AI Data Center Power Infrastructure Market Key Trends
- Expanding hyperscale AI campus construction continues accelerating demand for high-capacity UPS and switchgear systems.
- Growing adoption of 800-volt DC power architecture continues improving rack-level power delivery efficiency.
- Rising deployment of on-site fuel cells and gas turbines continues easing grid interconnection bottlenecks.
- Increasing utility transmission investment continues expanding dedicated power capacity for AI data center clusters.
- Growing vendor collaboration around unified reference architectures continues standardizing facility-to-chip power delivery.
Competitive Landscape
AI Data Center Power Infrastructure Market consists of global electrical equipment suppliers, UPS and power distribution solution providers, generators and fuel cell suppliers, transformer providers, and data center infrastructure technology solution providers competing against each other to cater to the fast-growing demand for power required for AI. The competitive differentiation lies around power density, quick deployment, manufacturing capabilities, grid integration, redundancy, 800VDC capability, modularity, on-site generation, and large-scale hyperscale campus capability.
In 2026, Bloom Energy signed a master services agreement with Oracle for up to 2.8 gigawatts of solid oxide fuel cell capacity to power AI data center campuses, expanding significantly from an earlier 1.2-gigawatt agreement. In 2026, Eaton disclosed nearly 20 pilot programs for its medium-voltage solid-state transformer technology supporting 800-volt DC distribution. Hyperscaler customer orders were expected in the second half of 2026, with shipments planned for late 2027.
Major key players include
Schneider Electric SE, Vertiv Holdings Co., Eaton Corporation plc, ABB Ltd, Delta Electronics, Inc., Legrand SA, Siemens AG, Hitachi Energy Ltd, Caterpillar Inc., Cummins Inc., Generac Holdings Inc., Rolls-Royce Power Systems AG, Toshiba International Corporation, Mitsubishi Electric Corporation, Socomec Group, Piller Power Systems Inc., Rittal GmbH & Co. KG, Huawei Digital Power Technologies Co., Ltd., Bloom Energy Corporation, EnerSys
Explore the Complete AI Data Center Power Infrastructure Market Report: https://www.snsinsider.com/reports/ai-data-center-power-infrastructure-market-10850
About Us:
SNS Insider is one of the leading market research and consulting agencies that dominates the market research industry globally. Our company's aim is to give clients the knowledge they require in order to function in changing circumstances. In order to give you current, accurate market data, consumer insights, and opinions so that you can make decisions with confidence, we employ a variety of techniques, including surveys, video talks, and focus groups around the world.
CONTACT: Contact Us:
Rohan Jadhav - Principal Consultant
Phone: +1-315-961-9094 (US)
Comments (0)
Login to join the conversation
Login / RegisterNo comments yet. Be the first to comment!