
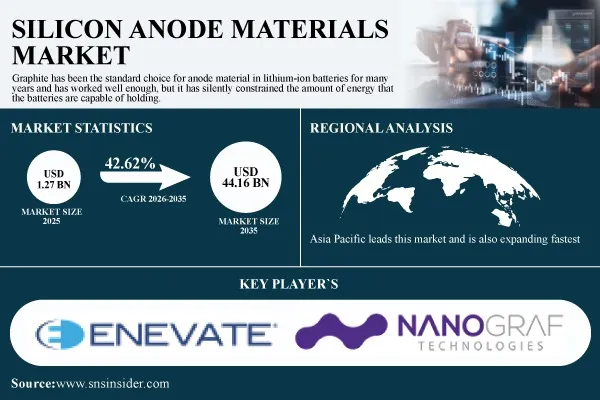
SNS Insider Estimates, the Silicon Anode Materials Market is projected to reach USD 44.16 billion by 2035, growing at a 42.62% CAGR, while the U.S. market is projected to reach USD 8.00 billion, advancing at 40.60% CAGR, as battery makers pursue higher energy density.
Austin, Sept. 30, 2026 (GLOBE NEWSWIRE) -- The global Silicon Anode Materials Market was valued at USD 1.27 billion in 2025 and is projected to reach USD 44.16 billion by 2035, expanding at a CAGR of 42.62% during 2026–2035. Gr The growth is fueled by the rise in the demand for batteries that have higher energy density. Lithium-ion batteries based on silicon are able to store more lithium theoretically than batteries based on graphite, while new developments in silicon-carbon composites and the production process can help overcome the problem of expansion.
The U.S. Silicon Anode Materials Market was valued at approximately USD 0.26 billion in 2025 and is projected to reach approximately USD 8.00 billion by 2035, growing at a CAGR of 40.60% during 2026–2035. The growth factors for the company are commercial-scale production facilities, government backing, collaboration with auto companies, and the establishment of a silicon anode manufacturing industrial cluster in Moses Lake, WA.
Get Exclusive Access to the Sample Report of Silicon Anode Materials Market Forecast @ https://www.snsinsider.com/sample-request/11165
The Europe Silicon Anode Materials Market was valued at approximately USD 0.29 Billion in 2025 and is projected to reach approximately USD 9.99 Billion by 2035, growing at a CAGR of approximately 40.80% during 2026–2035. Growth will be ensured by strict emissions control policies in Europe, development of regional networks for the battery value chain, and studies by European car manufacturers on silicon anodes to ensure more driving range, quicker charging times, and improved battery performance in EVs. The massive base of car manufacturing industry in Germany continues to drive the regional demand.
Why this Market is Gaining Attention in 2026
Electric Vehicle Range Requirements Are Raising Anode Performance Expectations
Automakers continue seeking higher battery energy density to increase driving range and reduce battery pack size and weight. Silicon can theoretically store substantially more lithium than conventional graphite, making it one of the most promising near-term anode materials for improving lithium-ion battery performance.
As EV manufacturers compete on range and charging performance, silicon anode materials are increasingly moving from laboratory development toward commercial qualification and large-volume supply agreements.
Gigawatt-Scale Manufacturing is Creating a Parallel Opportunity for Material Suppliers
The silicon anode industry is transitioning from pilot-scale production toward commercial factories capable of serving automotive and battery manufacturers at meaningful volume.
Facilities such as Sila Nanotechnologies' Moses Lake plant demonstrate that silicon anode technology is moving into industrial-scale manufacturing, creating opportunities for material suppliers, equipment providers and upstream raw-material companies.
Silane Supply and Production Innovation Expand the Market Opportunity
Silane gas remains an important input for several advanced silicon anode manufacturing processes and has historically represented a supply-chain bottleneck.
Dedicated silane production facilities and lower-cost manufacturing approaches are creating opportunities to improve supply security, reduce production costs and support broader commercialization of silicon anode materials.
For an In-Depth Strategic Briefing with Our Research Team, Connect Now @ https://www.snsinsider.com/request-analyst/11165
Commercial Findings from the Silicon Anode Materials Market
By Type, Silicon-Carbon Dominated and is also the Fastest Growing: Silicon-Carbon had a market share of around 64.60% in 2025, and is expected to register growth at a CAGR of about 44.60%. Its dominance is driven by the possibility of combining the high energy storage capacity of silicon and the structural stability of carbon to minimize degradation due to expansion of silicon.
By Application, Electric Vehicles Dominated and Energy Storage Systems are the Fastest Growing: Electric Vehicles represented approximately 44.60% of the market in 2025, driven by automakers seeking longer range and faster charging. Energy Storage Systems are projected to grow at the fastest CAGR of approximately 46.60%, supported by increasing renewable-energy integration and demand for higher-density stationary storage within constrained physical footprints.
By Production Process, Chemical Vapor Deposition Dominated and Ball Milling is the Fastest Growing: Chemical Vapor Deposition accounted for approximately 48.60% of the market in 2025, supported by precise control over particle structure and coating uniformity. Ball Milling is projected to grow at the fastest CAGR of approximately 43.60%, driven by its lower-cost and more scalable manufacturing profile as producers target mass-market applications.
Regional Battery Manufacturing Investment is Reshaping Market Demand: Asia Pacific leads the global Silicon Anode Materials Market and is also expanding fastest, supported by battery-cell manufacturing, silicon anode production and EV supply-chain concentration across China, South Korea and Japan. North America represents another significant market as government incentives and private capital accelerate domestic commercial-scale production.
Who Should be Watching the Silicon Anode Materials Market?
The market is increasingly relevant across the broader battery value chain, including:
EV manufacturers → battery cell producers → silicon anode developers → battery material companies → energy storage providers → consumer electronics manufacturers → silane suppliers → gigafactory operators → battery technology investors
For silicon anode suppliers, competitive positioning increasingly depends on energy density, cycle stability, swelling control, manufacturing scalability, raw-material security and the ability to qualify materials for high-volume automotive and battery applications.
Purchase Single User PDF of Silicon Anode Materials Market Intelligence Report @ https://www.snsinsider.com/checkout/11165
Commercial Manufacturing and Supply-Chain Investment Shape the 2026 Market
As silicon anode technology moves from pilot production toward commercial scale, companies are investing in raw-material infrastructure and higher-volume manufacturing.
- In 2024, Group14 received a USD 200 million U.S. Department of Energy grant to build a Moses Lake facility producing silane gas, an essential input for silicon battery materials.
- Amprius Technologies continued ramping production capacity following development of silicon anode battery technology with certified energy density reaching 500 watt-hours per kilogram.
Market Challenge: Controlling Silicon Expansion Without Increasing Cost and Manufacturing Complexity
Silicon can expand substantially during lithiation, creating mechanical stress that can crack electrodes and reduce battery cycle life. Controlling this expansion remains one of the industry's central technical challenges.
Production costs also remain higher than conventional graphite because silicon anode materials require specialized processes and stringent quality control. As a result, manufacturers are increasingly competing on swelling management, cycle stability, manufacturing efficiency and the ability to achieve commercial-scale economics.
Key Competitors in the Market
Companies covered in the Silicon Anode Materials Market research include Sila Nanotechnologies Inc., Group14 Technologies, Inc., Amprius Technologies, Inc., Enevate Corporation, NanoGraf Corporation, OneD Battery Sciences, NEO Battery Materials Ltd., Nexeon Ltd., Sicona Battery Technologies, BTR New Material Group Co., Ltd., Shin-Etsu Chemical Co., Ltd., POSCO Future M Co., Ltd., Daejoo Electronic Materials Co., Ltd., XG Sciences, Inc., NanoXplore Inc., California Lithium Battery Inc., Shenzhen BAK Power Battery Co., Ltd., GS Yuasa Corporation, Panasonic Holdings Corporation, and Advano.
About SNS Insider
SNS Insider is one of the leading market research and consulting agencies that dominates the market research industry globally. Our company's aim is to give clients the knowledge they require in order to function in changing circumstances. In order to give you current, accurate market data, consumer insights, and opinions so that you can make decisions with confidence, we employ a variety of techniques, including surveys, video talks, and focus groups around the world.
CONTACT: Rohan Jadhav - Principal Consultant
Phone: +1-315 636 4242 (US) | +44- 20 3290 5010 (UK)
Comments (0)
Login to join the conversation
Login / RegisterNo comments yet. Be the first to comment!