
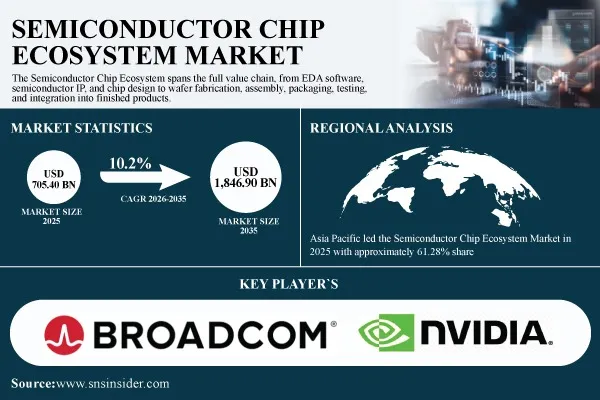
As per SNS Insider, the Global Semiconductor Chip Ecosystem Market is projected to reach USD 1,846.90 billion by 2035 as AI accelerators, advanced-node manufacturing, chip design, packaging and supply-chain localization reshape semiconductor investment
Austin, Sept. 21, 2026 (GLOBE NEWSWIRE) -- The global Semiconductor Chip Ecosystem Market was valued at USD 705.40 billion in 2025 and is projected to reach USD 1,846.90 billion by 2035, expanding at a CAGR of 10.2% during 2026–2035. Demand will be driven by AI infrastructure investments, advances in semiconductor fabrication technology, electronic design automation tools, semiconductor intellectual property, foundry investments, advanced packaging, and semiconductor supply chain localization.
The U.S. Semiconductor Chip Ecosystem Market was valued at approximately USD 152.80 billion in 2025 and is projected to reach approximately USD 385.20 billion by 2035, growing at a CAGR of approximately 9.7%. Growth is supported by fabless semiconductor design expertise, electronic design automation leadership, hyperscale artificial intelligence infrastructure investment, and domestic wafer fabrication capacity.
Download the Semiconductor Chip Ecosystem Market Sample Report: https://www.snsinsider.com/sample-request/10961
Why this Market is Gaining Attention in 2026
AI Infrastructure is Increasing Pressure Across the Semiconductor Value Chain
The semiconductor chip ecosystem opportunity is increasingly tied to AI infrastructure investment rather than just chip volumes. The increased usage of GPUs, AI accelerators, and Semiconductor Chip Ecosystem is driving up the demand for manufacturing advanced node processes, electronic design automation, semiconductor IPs, foundry capacity, and advanced packaging.
The interdependencies within the semiconductor value chain mean that any bottlenecks or capacity limits in advanced packaging, extreme ultraviolet (EUV) lithography, and high-bandwidth memory will affect downstream capacity, even when excess capacity exists in other parts of the chain.
Fab Expansion is Creating a Parallel Opportunity Across the Supply Chain
Government-backed manufacturing investments are driving the rapid expansion of semiconductor fabrication facilities in the US, Europe, India, Japan, and South Korea. Building new fabrication facilities requires not only wafer fabrication equipment but also design tools, materials, semiconductor intellectual property (IP), packaging facilities, test facilities, and suppliers.
Thus there are opportunities across the entire ecosystem of the semiconductor industry including foundry companies, integrated device manufacturers, outsourcing assembly and test companies, equipment companies, and design technology companies.
Advanced Packaging and Chiplet Architectures Expand the Ecosystem Opportunity
The opportunity is expanding beyond traditional monolithic semiconductor fabrication. Advanced packaging techniques, such as CoWoS, SoIC, hybrid bonding and chiplets are playing an increasingly crucial role in the manufacture of AI accelerators and HPC solutions.
These techniques facilitate the integration of separate dies produced using different processes into a single package, creating opportunities for foundries, OSATs, and interconnect and packaging companies across the semiconductor supply chain.
Buy the Semiconductor Chip Ecosystem Market Report (20% Discount) with Competitive Analysis and 2035 Forecast: https://www.snsinsider.com/checkout/10961
Commercial Findings from the Semiconductor Chip Ecosystem Market
Wired Communication Dominated and Wireless Communication is the Fastest Growing Segment: Wired communication accounted for about 54.20% of the communication market in 2025, thanks to networking of data centers, optical transport and enterprise switching infrastructure. Wireless communication is the fastest-advancing segment and is expected to grow at a CAGR of about 12.8%, driven by 5G network densification, IoT adoption, next-generation Wi-Fi and rising connectivity demands across industry, wearables and automotive applications.
Consumer Electronics Dominated and Healthcare Equipment is the Fastest Growing Application: The consumer electronics industry held about 29.65% market share in 2025, due to the substantial presence of semiconductors in smartphones, computers, wearable tech products and smart home devices. The healthcare equipment industry is the fastest-growing segment and is expected to expand at a CAGR of about 13.9%, driven by medical imaging, wearables, implantable medical devices, and related technologies.
Regional Manufacturing Investment is Reshaping the Semiconductor Ecosystem: The Asia Pacific region dominated with about 61.28% of the Semiconductor Chip Ecosystem Market share in 2025 due to the presence of highly localized foundries, memory production, packaging and semiconductor manufacturing in Taiwan, South Korea, China and Japan. The North American region is projected to record the highest CAGR of 12.6% owing to CHIPS Act enabled fab development, hypershaper AI investments and semiconductor designing prowess in this region.
Who Should be Watching the Semiconductor Chip Ecosystem Market?
The market is increasingly relevant across the broader semiconductor value chain, including:
Fabless chip companies → integrated device manufacturers → foundries → semiconductor IP providers → EDA software companies → advanced packaging providers → OSAT companies → semiconductor equipment suppliers → materials suppliers
The opportunity for semiconductor firms extends beyond increasing wafer production capacity. Competitiveness depends on design expertise, access to state-of-the-art production, advanced packaging, semiconductor intellectual property, and resilient, coordinated supply chains across multiple layers of the ecosystem. From a downstream tech firm perspective, constraints within a particular layer of the semiconductor sector may affect product availability and deployment timelines.
Do you have any specific queries or need any customized research on Semiconductor Chip Ecosystem Market? Schedule a Call with Our Analyst Team @ https://www.snsinsider.com/request-analyst/10961
Semiconductor Manufacturing Investments and Ecosystem Expansion Shape the 2026 Market
As semiconductor demand becomes increasingly connected to AI infrastructure and geopolitical supply-chain priorities, companies are expanding domestic fabrication, advanced packaging and design capabilities.
- In 2026, TSMC committed an additional USD 100 billion to its Arizona operations, bringing its total declared U.S. investment to USD 265 billion to support additional sub-2nm fabs and advanced packaging facilities.
- In 2026, NVIDIA and TSMC expanded their collaboration to apply AI across semiconductor design and manufacturing, including computational lithography, process simulation, automated defect inspection and fab operations optimization.
Market Challenge: Expanding Semiconductor Capacity Without Increasing Capital and Supply-Chain Risk
The most advanced semiconductor manufacturing technologies require substantial capital investments, as reaching volume production may cost billions of dollars and take many years. Delays related to manufacturing construction and qualification will pose challenges to capacity build-out efforts and put additional pressure on semiconductor firms and governments' incentive programs.
Geopolitical export restrictions and concentrated manufacturing capacity add another layer of difficulty. Reliance on narrow groups of suppliers in such key semiconductor technologies as advanced lithography, manufacturing capacities and others make the whole ecosystem vulnerable to region-related disturbances and policy changes. As a result, semiconductor companies are now competing on manufacturing scale, supply chain resilience, and advanced technologies.
Key Competitors in the Market
Companies covered in the Semiconductor Chip Ecosystem Market research include Taiwan Semiconductor Manufacturing Company Limited (TSMC), Samsung Electronics Co., Ltd., Intel Corporation, SK hynix Inc., Micron Technology, Inc., NVIDIA Corporation, Qualcomm Incorporated, Broadcom Inc., Texas Instruments Incorporated, GlobalFoundries Inc., United Microelectronics Corporation (UMC), Semiconductor Manufacturing International Corporation (SMIC), ASE Technology Holding Co., Ltd., Amkor Technology, Inc., ASML Holding N.V., Applied Materials, Inc., Synopsys, Inc., Cadence Design Systems, Inc., and Arm Holdings plc.
Explore the Complete Semiconductor Chip Ecosystem Market Report: https://www.snsinsider.com/reports/semiconductor-chip-ecosystem-market-10961
About Us:
SNS Insider is one of the leading market research and consulting agencies that dominates the market research industry globally. Our company's aim is to give clients the knowledge they require in order to function in changing circumstances. In order to give you current, accurate market data, consumer insights, and opinions so that you can make decisions with confidence, we employ a variety of techniques, including surveys, video talks, and focus groups around the world.
CONTACT: Contact Us:
Rohan Jadhav - Principal Consultant
Phone: +1-315-961-9094 (US)
Comments (0)
Login to join the conversation
Login / RegisterNo comments yet. Be the first to comment!